
Hello Measured Investors,
Welcome to The Measured Memo, a concise note that shares our perspective on private investing and income-producing assets. We aim to make this the most value-packed investing read of your quarter. Let’s go!
Market
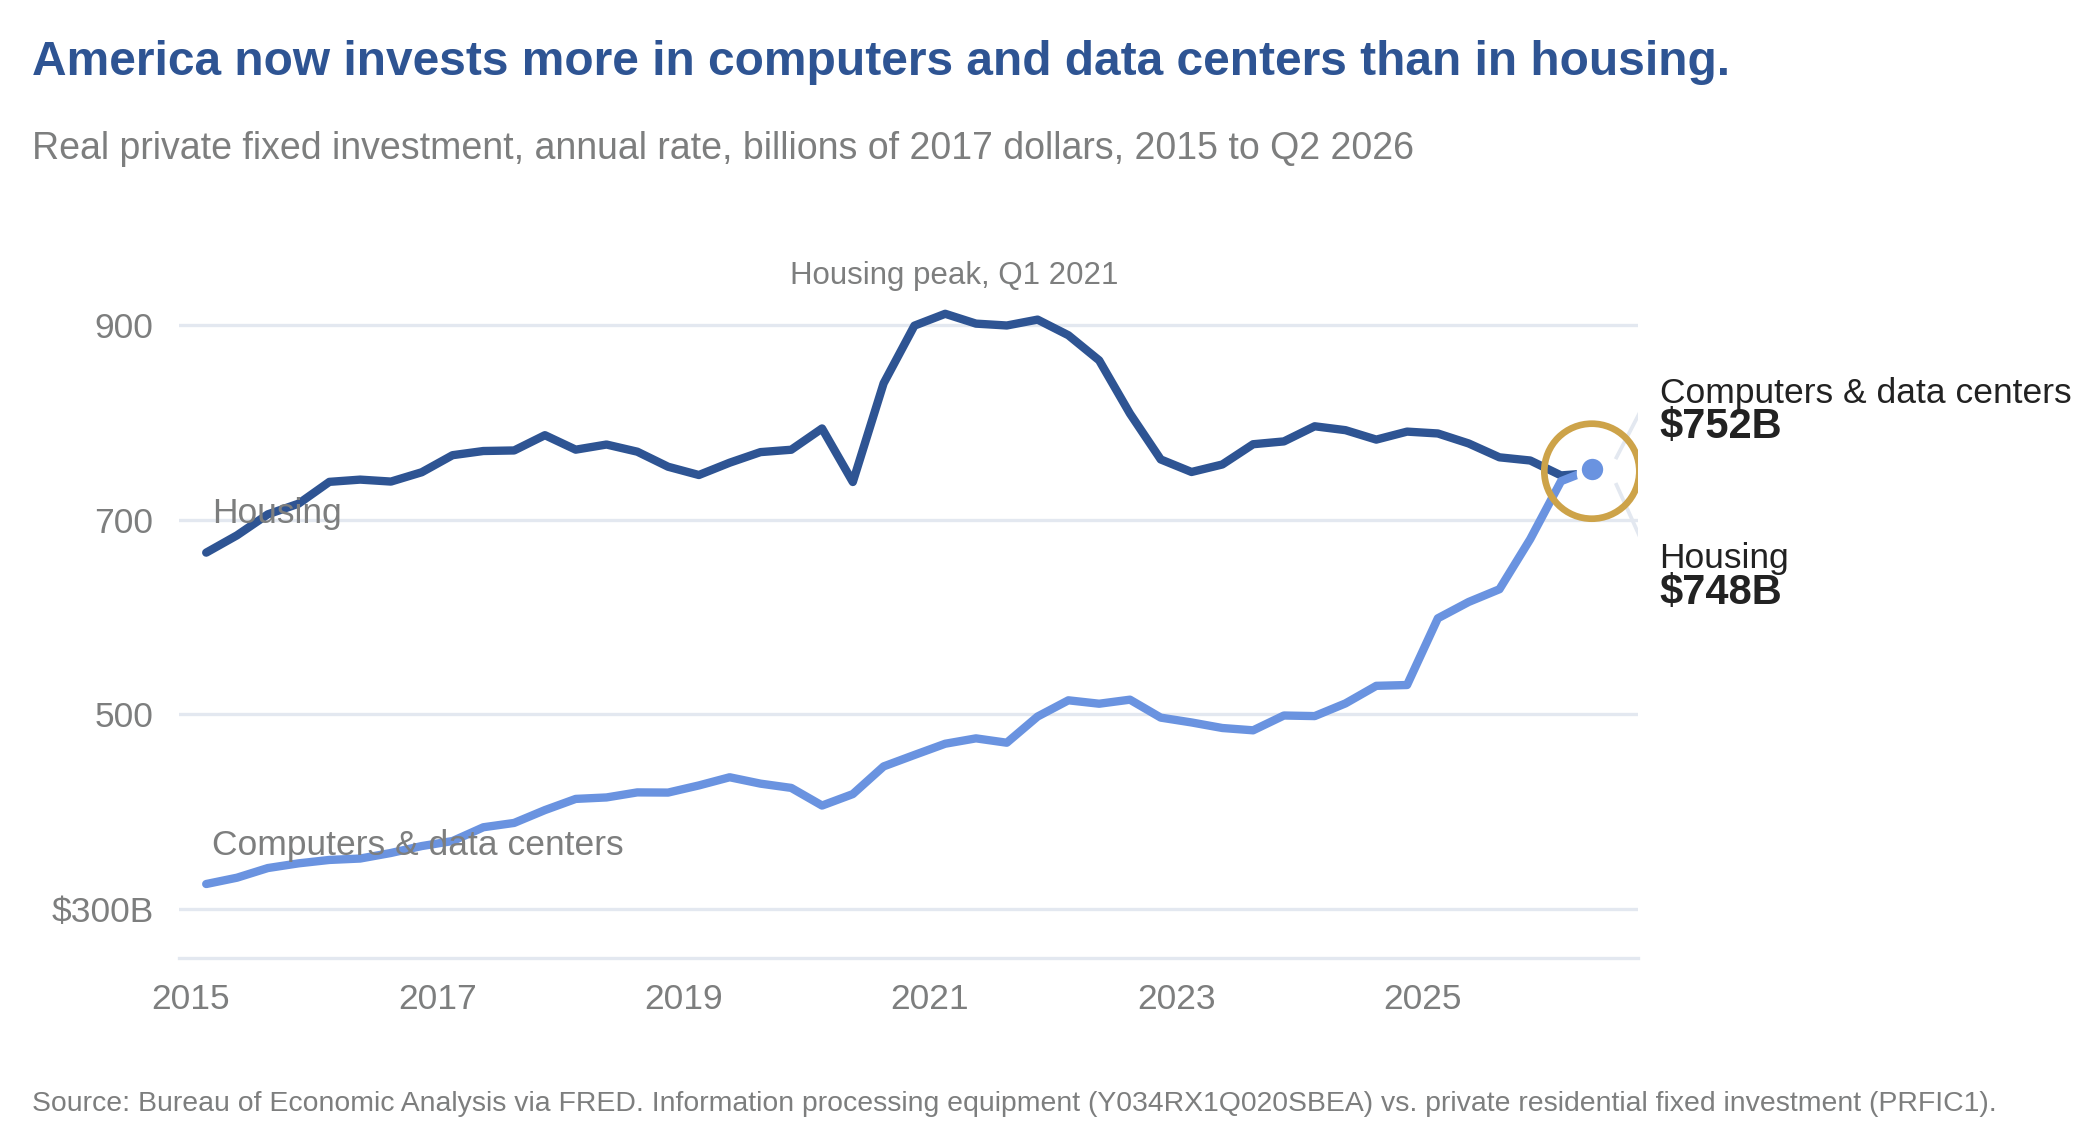
If your portfolio is having a good year, one story probably did most of the work: AI. In the second quarter, for the first time on record, America invested more in computers and data centers than in housing, and by most estimates that build out accounted for up to three-quarters of economic and corporate earnings growth this year. We use these tools every day and we will show you how. First, let’s look at the impact on investment markets.
The growth is hyperbolic yet the economics underneath it are still undefined. We know what it costs to build a datacenter, but nobody knows exactly how they will be monetized long-term. History contains some important examples: railroads in the 1870s, electricity in the 1920s, fiber in 2000. Booming demand, real technology, and every time we built far more, far faster, than demand could absorb.
We are not calling a top or discouraging anyone from owning AI companies. We are saying the S&P 500 trades at a cyclically adjusted P/E of 40.7, a level reached only once before, in 1999. That is a market high on hopes. The same appetite has reached the debt markets, where AI projects will borrow at almost any cost, one major reason interest rates have stayed high for everyone else, real estate included.
Our conclusion is that cycles will cycle, as they always do. Bottoms become tops and tops become bottoms. Some AI companies will fail, some will boom, and nobody knows which will be which. Apartments and warehouse space have been useful for centuries, and by the Lindy Effect (the longer something has been around, the longer it is likely to last) they will be useful long after this build out is right-sized. When capital crowds into the unproven, the proven is usually a better value, and that is where our strategy starts.
Strategy
None of this says we don’t believe in the disruptive power of AI, in fact, quite the opposite. The railroad bust wiped out the people who financed the tracks and made a fortune for the people who shipped freight on them, at a discount, for the next fifty years. We intend to be the shipper. About eighteen months ago we decided sitting this wave out was the riskier choice and have been rebuilding how our company operates ever since. It has leveled the field: work that once took a large operator’s back office now runs faster with fewer hands.
What that looks like in practice: our rent comp dashboard sets asking rents from live market data instead of a property manager’s gut, our KPI dashboards flag a operational variance the day it happens, and our rebuilt property websites turn more visitors into tours and show us where a pipeline is leaking before it costs us in vacancy.
None of this replaces people; it lets them spend their time on relationships and the decisions that move results. The tools change how we work, not the service we provide or the value to our customers. The posture we take with our own capital is the one we suggest for yours: enjoy the tools, be careful with the mania, and keep allocating to assets that have proven useful for centuries.
Portfolio
The results are showing up. Across more than 1,100 units, same property revenue is up 6% year over year, and net operating income is up 14%. Our Des Moines portfolio just had its best quarter on record, with higher occupancy, better collections and lower expense ratios. Jacksonville is performing well under new management, and we are seeing strong demand for our communities with combined occupancy at 96%. The townhome community we added in Des Moines, bought directly from the family that built it, is 100% occupied and ahead of plan.
AI did not produce those numbers. People did, with decisions made in week one instead of week five because the information now arrives in real time. We often say this is the difference between playing offense and defense, and we much prefer being on offense.
Looking ten years out, into an economy AI has reshaped, one segment of businesses we expect to thrive are those with a service element and a physical footprint: the HVAC company, the parts distributor, the light manufacturer bringing work back onshore. They are not being disintermediated; they are getting more productive and more profitable.
That is why we are adding light industrial assets to our portfolio: apartments for service business, with many tenants under one roof, rolling leases, the same operating playbook we already run. The tenants in these properties cover their own taxes and maintenance costs and sign leases that last for years instead of months. It also answers the hardest lesson of the past four years in multifamily: supply. Over the past decade, employment in the industries that use light industrial space has grown 20% while the supply of new buildings grew 3%.
Our conviction in apartments has not changed: our residents will have work and will pay rent. The question we’re asking ourselves is whether apartments benefit from AI the way a contractor’s bay does. Owning both is how we hedge that bet without leaving our lane.
We are acquiring our first light industrial portfolio, our fifth major investment in Des Moines, in a high traffic pocket of the metro, closing later this month. It’s an off-market transaction on a portfolio that is 100% occupied and produces great cash flow from day one.
References
- Financing the AI Buildout – Brookings Institution, September 2026: $10.3 trillion through 2032, a larger share of GDP than the railroads, the interstates or the fiber build-out.
- Workers’ Exposure to AI: What Indicators Tell Us and What They Don’t – International Labour Organization, February 2026, on which occupations carry the most and least AI exposure.
- Shallow-Bay Industrial Availability Remains Tight Amid Strong Demand – CBRE, March 2026, on how little light industrial product has been built since 2010.
Thanks for reading. At Measured Capital, we are committed to always putting ourselves in the place of highest potential, which for us, often means connecting with like-minded investors like you.
Please forward this note to any trusted friend you feel could benefit as well. We welcome your feedback and are grateful for your trust.
Best,
Dan & Greg